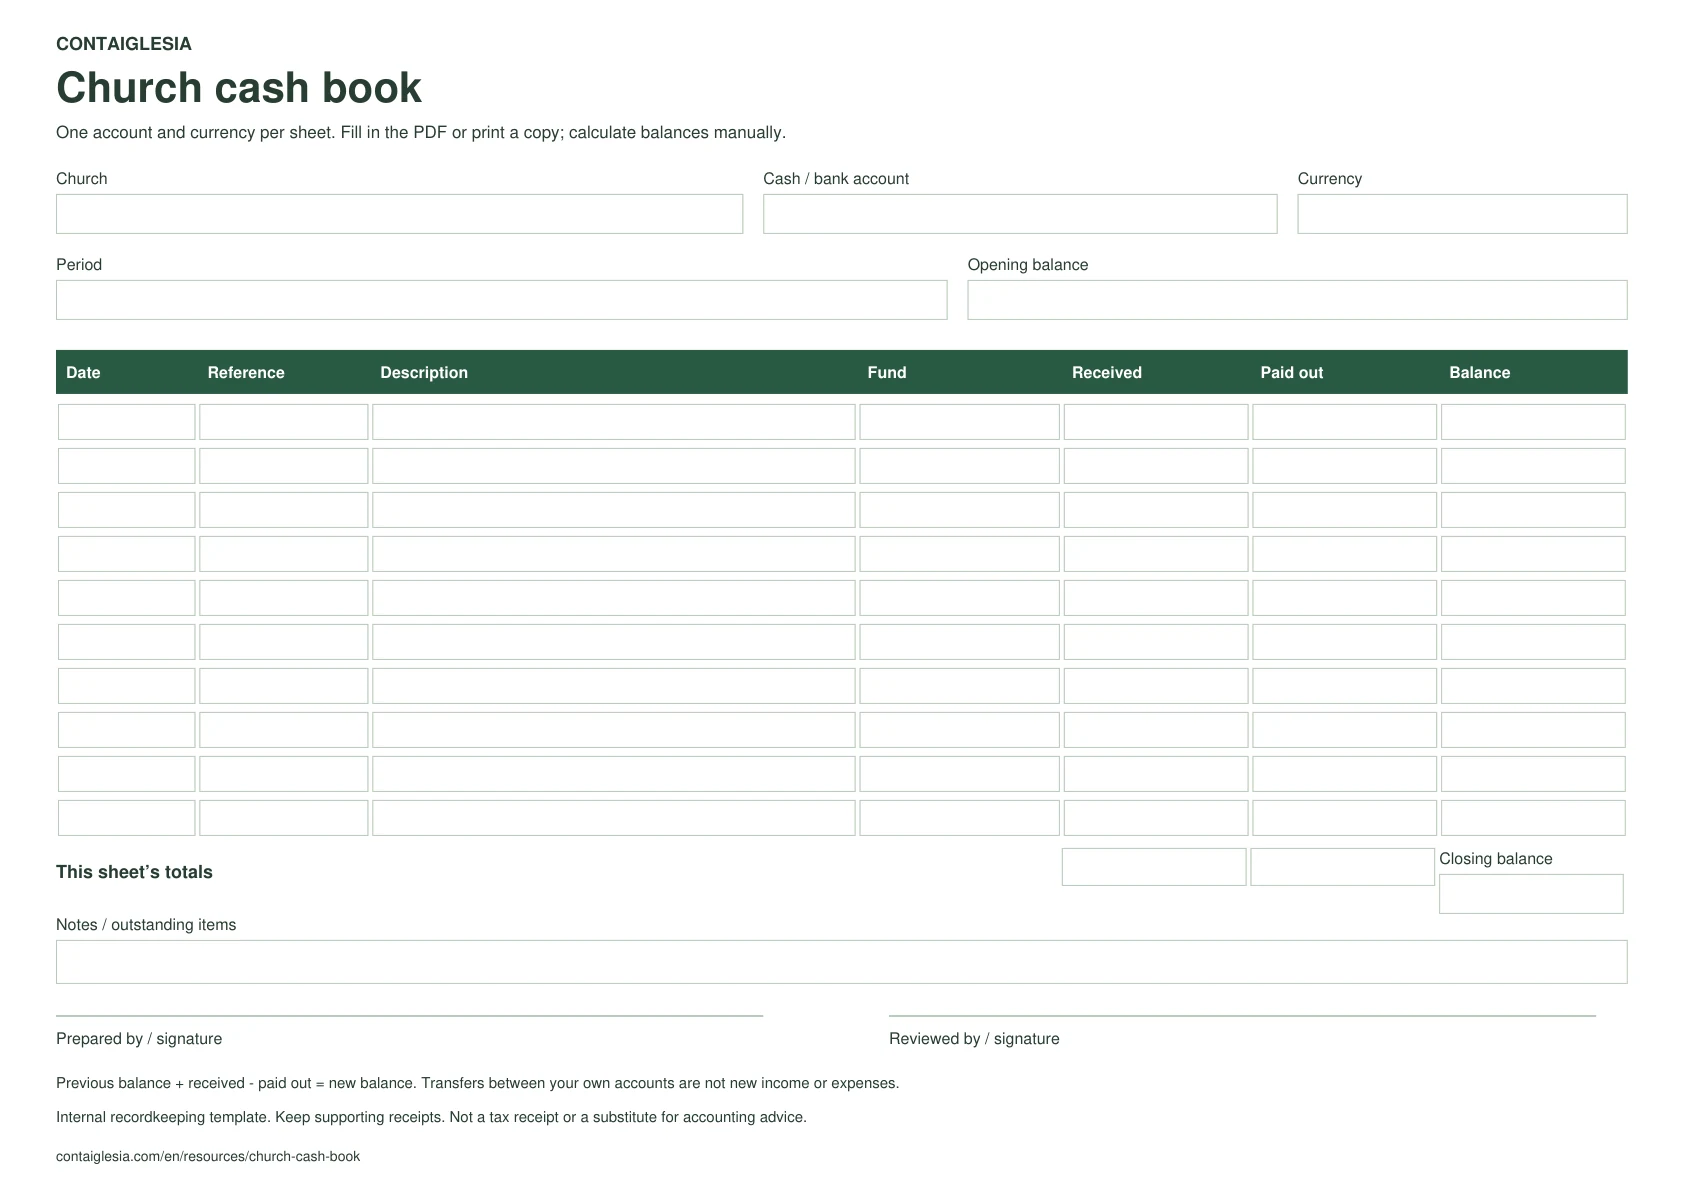
What this sheet records
- One specific account, such as General cash or Main bank account. Keep separate sheets for cash and bank, and match the references on transfers between them.
- One currency. Amounts in dollars and pesos cannot be added together without a separate conversion record. Identify the currency beside the account name.
- Money that has actually moved. An offering pledge or an unpaid purchase does not change this sheet’s balance.
Five transactions and a balance you can check
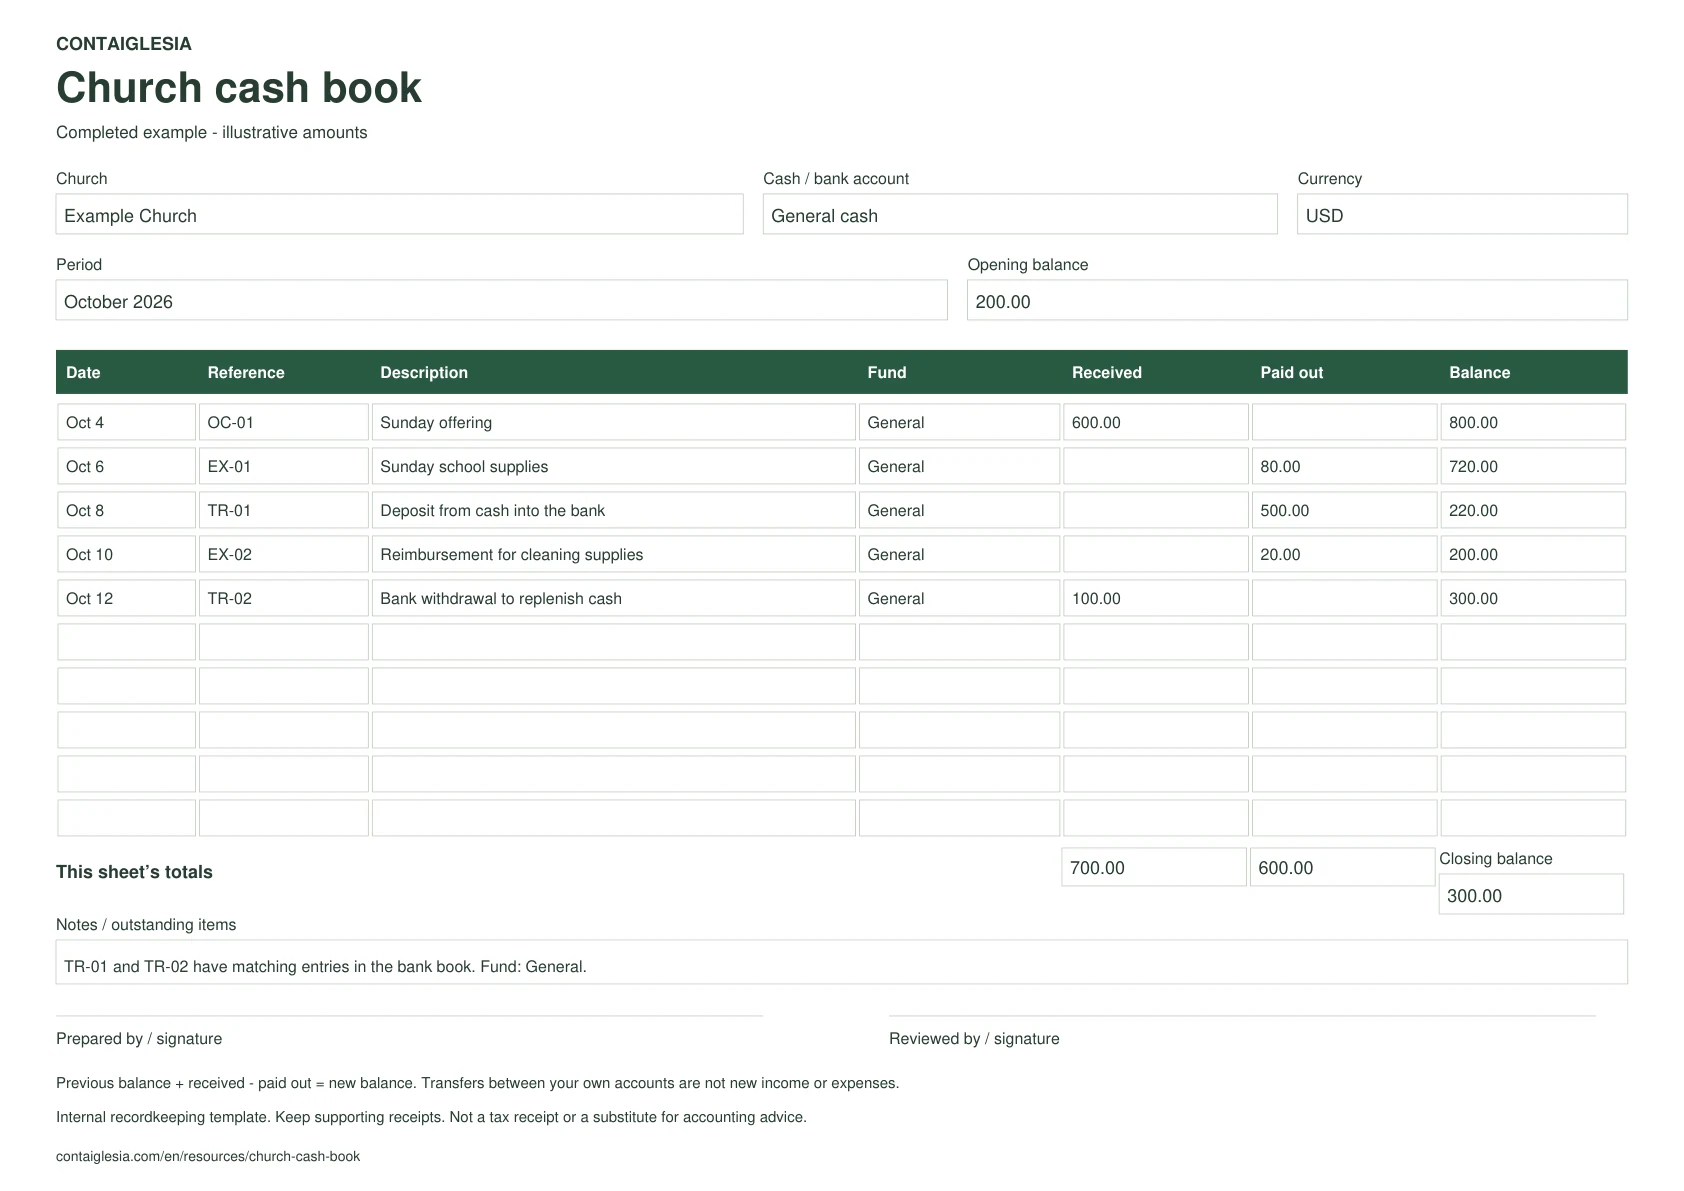
An illustrative October example in US dollars. Cash starts at USD 200.00 and the bank at USD 800.00. Transfers change where the money is held, without creating income or an expense.
- Oct 4
Sunday offering
Reference: OC-01 · General- Received
- 600.00
- Paid out
- —
- Balance after
- 800.00
- Oct 6
Sunday school supplies
Reference: EX-01 · General- Received
- —
- Paid out
- 80.00
- Balance after
- 720.00
- Oct 8
Deposit from cash into the bank
Reference: TR-01 · GeneralInternal transfer- Received
- —
- Paid out
- 500.00
- Balance after
- 220.00
- Oct 10
Reimbursement for cleaning supplies
Reference: EX-02 · General- Received
- —
- Paid out
- 20.00
- Balance after
- 200.00
- Oct 12
Bank withdrawal to replenish cash
Reference: TR-02 · GeneralInternal transfer- Received
- 100.00
- Paid out
- —
- Balance after
- 300.00
- Cash received
- USD 700.00
- Cash paid out
- USD 600.00
- Closing cash balance
- USD 300.00
View the completed example
Money leaving cash is not always an expense
Deposit TR-01 reduces cash by USD 500.00 and increases the bank balance by the same amount. It is neither another expense nor another offering. Withdrawal TR-02 moves USD 100.00 in the opposite direction. Use the same transfer reference in both accounts.
- Closing cash balance
- USD 300.00
- Closing bank balance
- USD 1,200.00
- Cash + bank
- USD 1,500.00
The combined balance moves from USD 1,000.00 to USD 1,500.00: an offering adds USD 600.00 and expenses use USD 100.00. Internal transfers do not change this total.
Complete the book, then check the balance
Identify the account and opening balance
Enter the church, account, currency and period. Check the opening balance against the previous closing balance; do not also record it as money received.
Keep each entry tied to its evidence
Record the date, reference, description, fund and amount received or paid out. Add receipts to the previous balance and subtract payments. This PDF does not calculate balances automatically.
Compare the closing balance with the actual account
For cash, count the money held. For a bank account, compare the statement and review outstanding transactions. Investigate any difference before marking the period as checked.
What the cash book does not replace
Keep the offering count, supporting receipts and bank reconciliation alongside this record. A fund describes the purpose assigned to money; an account describes where it is held. A cash book alone is not a category report, a donor statement or proof of tax compliance. Adapt the review to your church’s responsibilities and local requirements.
Questions about this template
Is this an Excel cash book?
This download is a fillable PDF, not an Excel file. Use the income and expense spreadsheet linked below if you need formulas and a category summary.
Is every cash receipt church income?
No. An offering received is income, while a withdrawal from the church’s own bank account is an internal transfer into cash. Keeping that distinction avoids counting the same money twice.
What happens after the ten rows are full?
Continue on another sheet for the same account and period. Carry the first sheet’s closing balance forward as the next opening balance; do not add it again to money received.
Can I complete the PDF on a phone?
You can open it in a browser. To fill in and save the fields, use a PDF reader that supports forms. Save a copy and reopen it to check that your entries were retained.
Recordkeeping reference
Scotland’s charity regulator, OSCR, lists cash books, bank statements and supporting evidence as complementary records. This page draws on that organizational principle; legal requirements vary by jurisdiction. OSCR: Accounting records