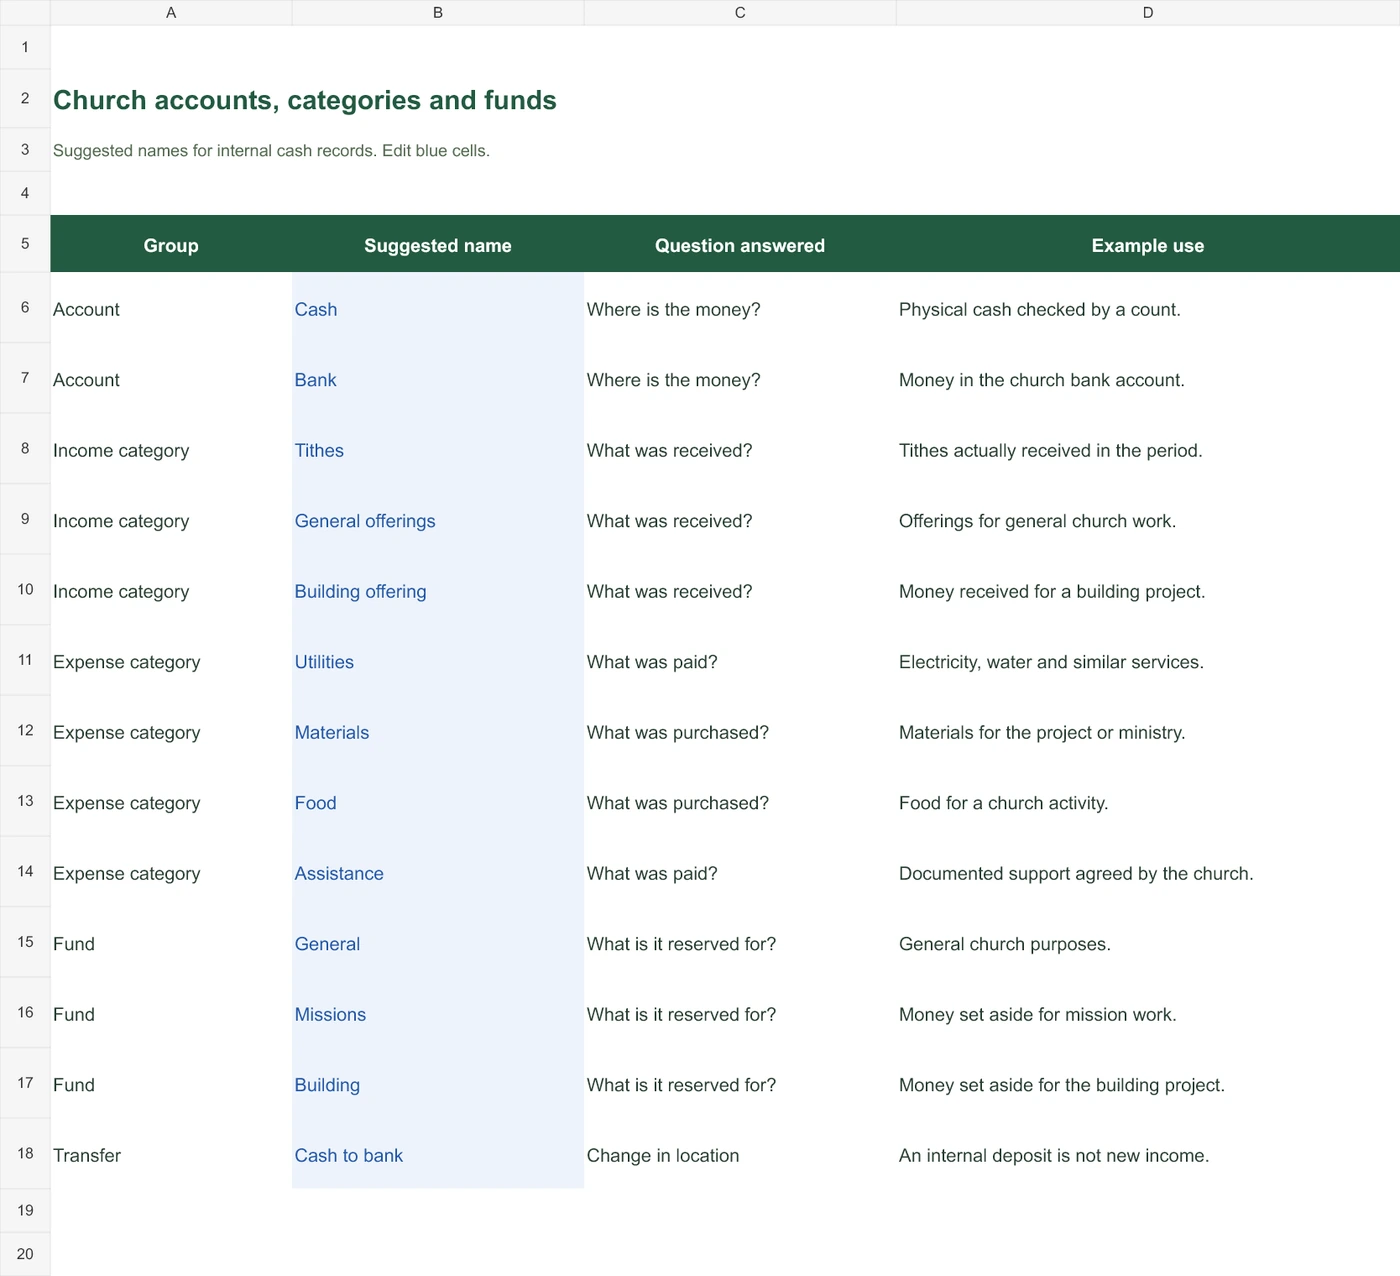
Three questions before creating an account
Account: Where is the money?
Cash is money you can count. Bank is money held in the church’s bank account. Match each name to a real account you review.
Category: What was received or paid?
Tithes, offerings, utilities and materials describe transactions. A category helps explain the activity for the period; it is not another pot of money.
Fund: What is the money reserved for?
General, missions and building identify purposes. One bank account may contain several funds. Moving money to the bank does not change its agreed purpose.
One offering, three different details
Start with USD 200.00 in cash and USD 800.00 in the bank. Of the same USD 1,000.00, the general fund holds 700.00 and missions holds 300.00. The account view and the fund view explain the same money.
- COL-014
Offering received
- Account
- Cash
- Category
- Offerings
- Fund
- Missions
- Amount
- $300.00
- MAT-006
Mission materials
- Account
- Cash
- Category
- Materials
- Fund
- Missions
- Amount
- $120.00
- DEP-014
Internal deposit
- Account
- Cash → Bank
- Category
- —
- Fund
- Missions
- Amount
- $250.00
The deposit retains the missions designation and is not another offering. Categories describe the income and expense. The transfer changes where part of the money is held.
Where the money is held
- Cash
- $130.00
- Bank
- $1,050.00
- Total
- $1,180.00
What it is set aside for
- General
- $700.00
- Missions
- $480.00
- Total
- $1,180.00
Cash and bank total USD 1,180.00. General and missions also total USD 1,180.00. Do not add the two views together: the church does not hold USD 2,360.00.
Fictional classification example. The workbook includes this example and its balance formulas. It is not an ongoing transaction ledger or an automatic connection to ContaIglesia.
Adapt the list with your team
- Keep the account names that correspond to actual cash or bank accounts. Avoid opening a second entry for the same bank account just because two people refer to it differently.
- Choose a small, understandable set of income and expense categories. Agree whether similar purchases belong under Materials or another category, so the same activity is not split between several spellings.
- Create a separate fund when you need to preserve and review a purpose and its balance. A ministry name alone does not mean it needs another bank account or a separate set of books.
- Have another team member classify the three sample transactions. Resolve differences in the naming before transferring a full history. Preserve older names and references when changing existing records; do not erase their explanation.
What this workbook does
The Accounts tab is an editable list of suggestions. The Example tab calculates the closing cash, bank, general and missions balances from its seven sample inputs. The Instructions tab explains what can be changed.
This is a starter for internal cash records, not a complete statutory chart of accounts or a set of financial statements. Assets, liabilities, payroll and formal reporting may require a fuller structure agreed with the church’s accountant.
The sample uses USD. Enter figures in a single currency; changing a currency label does not convert values. The file does not import into or synchronize with ContaIglesia.
Keep the amount cells numeric and preserve the formulas. An empty required input leaves its dependent balance blank; zero is a valid amount. Review any difference between the opening account and fund totals before relying on the example.
Questions about the file
Is this a full church chart of accounts?
It is a simple account, category and fund list for internal cash records, with a worked example. It does not define a full double-entry chart, legal account codes or your church’s formal reporting obligations.
Can one offering have both a category and a fund?
Yes. In the example, the money is held in Cash, classified as an Offering and set aside for Missions. Those labels explain different aspects of one receipt; they are not three income entries.
Do I need a bank account for every ministry?
The example keeps General and Missions money within the same cash and bank holdings. Whether a church needs separate bank accounts depends on its own arrangements. A designation should remain traceable whichever account holds the money.
Can I keep individual contribution details as well?
Yes, but keep the personal detail separate from the category totals and restrict access appropriately. If individual contributions are already included in the collection total, recording them again as new income would duplicate the money.
Can I add more rows?
You can extend the list of suggested names. The balance formulas on the Example tab cover only its three illustrated transactions; adding a transaction row does not automatically extend those formulas. Use a transaction ledger for ongoing records.
Concept reference
Terminology reference from another system. The workbook and amounts on this page are an original ContaIglesia example.